Independent guide · Payments
Why a card refund can be pending — and when it will post
Clear, evidence‑based explanation of where delays happen when a merchant refunds a card payment, what “pending” means, and practical steps to get a missing credit posted.
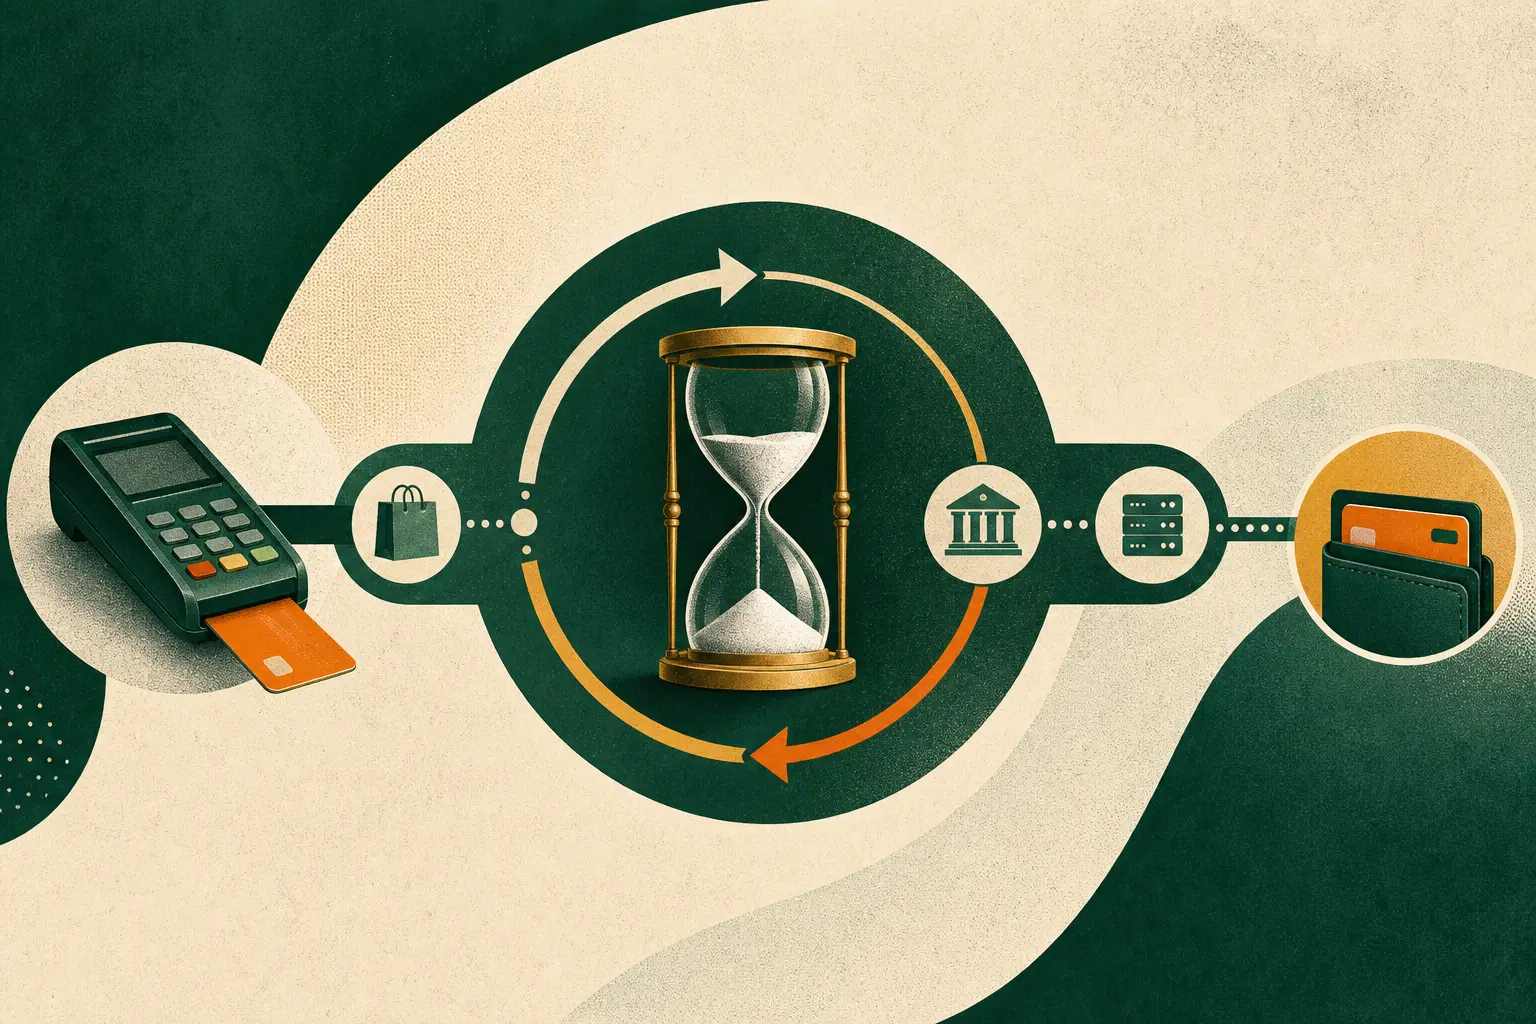
Merchant refunds flow from merchant → acquirer → card network → issuer. Visibility and timing vary: a pending credit often appears quickly, but posting to your statement depends on issuer processes and reconciliation.
How a card refund actually flows and where delays happen
A merchant creates a refund instruction (credit voucher or return authorization) and sends it to its acquiring bank. The acquirer forwards the refund through the card network (Visa/Mastercard) to the issuing bank that holds the consumer’s card account.
Delays can happen at several points: the merchant or acquirer may take time to prepare and transmit the refund; the network may route and reconcile messages; and the issuer must receive, match and post the credit to the cardholder’s account. Any of these steps can add days.
- Merchant → acquirer → network → issuer is the standard flow.
- Processing delays can occur at merchant/acquirer, in network reconciliation, or at issuer posting.
What “pending” or provisional credits mean
Your card app may show a pending credit when the merchant or acquirer has acknowledged the refund. That pending entry usually reflects receipt of the refund message but is not always the final, posted credit on your billing statement.
Issuers and networks sometimes place provisional credits while they verify the refund or investigate a dispute. A provisional credit can be reversed if the issuer later determines the refund was not valid or if the merchant contests the return.
- Pending = acknowledgement; posted = final accounting on your statement.
- Provisional credits can be reversed after investigation.
Typical timing windows (industry guidance and why ranges vary)
Card networks and issuers do not publish a single guaranteed number of days. Visa advises merchants to tell customers credits may take “a few days” to appear; Mastercard explains the timeline depends on the cardholder’s bank. Regulators (CFPB/Regulation Z in the U.S.) set procedural rules but do not mandate a universal posting time.
In practice, consumers often see a pending credit within 24–72 hours of merchant processing and a posted credit within a few business days; some issuers or edge cases (reissued cards, single‑use tokens, BNPL flows) can take up to around two weeks to appear as a posted credit.
- Visa: “a few days” for visibility (merchant guidance).
- Mastercard: timing depends on the cardholder’s bank.
- CFPB/Regulation Z: issuer posting procedures allow some operational leeway.
Common reasons a refund might not appear or may disappear
The merchant may never have submitted the refund, or it may have submitted it to the wrong card or account. Merchants sometimes issue store credit, gift cards, or other non‑card refunds, especially if the original card has been replaced or expired.
Other reasons include routing to a single‑use or virtual token that cannot accept standard credits without extra steps, a provisional credit later reversed after investigation, or processing errors at the acquirer or issuer. These are documented in card network guidance and CFPB reports.
- Merchant failed to submit the refund.
- Refund sent to wrong card/account or to a token that doesn't accept credits.
- Merchant issued non‑card credit (store credit/gift card) instead.
- Provisional credit reversed after investigation.
Practical checklist
- Keep the merchant’s refund confirmation (email or in‑app) with refund ID and date.
- Check your issuer’s pending activity and account daily for a few business days.
- If pending disappears or no posted credit appears, ask the merchant for the refund transmission ID and date.
- Contact your card issuer and request a trace of the refund; provide the merchant’s refund confirmation.
- If unresolved in the U.S., file a complaint with the CFPB or follow your issuer’s dispute process.
Sources and further reading
Fact-checked: . External sources open in a new tab.
- Processing Refunds to Cardholders in a Merchant Store Location (merchant guidance)Visa
- Chargeback guide and refund timing guidanceMastercard
- Regulation Z — credit card provisions and posting rulesConsumer Financial Protection Bureau (CFPB)